AC replacement financing may let you spread the cost of a new system over time, subject to lender approval and current terms. Start with an itemized replacement estimate, then compare the APR, fees, term, monthly payment, and total amount you would repay. A low monthly payment means little if it does not cover the full installation or costs much more over time.
When an AC fails during a Boca Raton summer, it is understandable to focus on getting cooling back quickly. Taking a little time to compare the project scope and financing terms can help you avoid paying for missing work or choosing a plan based only on the monthly number.
Often, yes. HVAC financing is generally offered through a third-party lender, not directly by the contractor. The lender controls the application, approval decision, credit requirements, rates, and repayment terms.
Before applying, get the complete replacement cost in writing. Once you know how much the project will cost, you can consider the financing options currently available and decide whether any of them fit your budget.
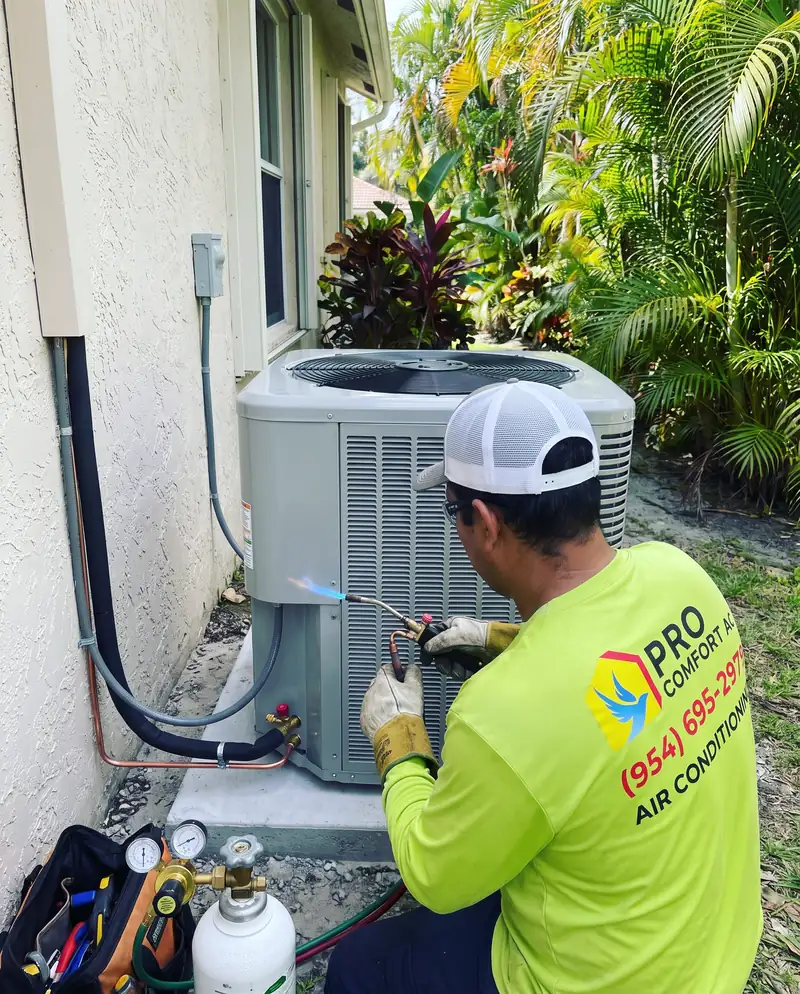
Financing only makes sense when it covers the work your home needs. An itemized estimate should identify the indoor and outdoor equipment, permit, electrical work, drain and safety switches, thermostat, duct corrections, access needs, removal of the old system, startup, and warranty coverage when each item applies.
A complete AC replacement should also identify the matched equipment being installed. Access, electrical updates, ductwork, and equipment choice can all change the final project cost.
If you are collecting more than one estimate, compare what each AC quote includes before looking at financing. Similar monthly payments can represent very different equipment and installation work.
The process usually moves from the replacement estimate to the lender application and then to installation scheduling. The exact steps and timing depend on the lender.
Applying does not guarantee approval, and an advertised rate may not be the rate offered to every applicant. Read the lender’s final disclosure before accepting the agreement.
It can. Some lenders use a soft credit inquiry for prequalification and a hard inquiry for a full application. Ask which type will be used before submitting your information.
There is also no single credit score that guarantees approval. Lenders may consider your credit history, income, existing obligations, requested amount, and other factors. A stronger application may qualify for better terms, but the lender decides what is available.
These offers can look similar in an advertisement but work very differently once repayment begins.
APR is the yearly cost of borrowing, shown as a percentage.
True 0% financing charges no interest when you follow the agreement’s terms.
Deferred interest allows interest to build during the promotional period. If the balance is not paid as required by the deadline, the accrued interest may be added.
Also look at the loan term, fees, early-payoff rules, late-payment consequences, and total amount repaid. The monthly payment alone does not show the full cost.
Here is what the same $9,800 AC replacement could cost under different payment structures. These numbers are examples for comparison, not current financing offers.
Pay cash
$9,800 upfront
Total Paid$9,800
Financing Cost$0
Why It MattersLowest total cost, but requires paying the full project price at once.
True 0% financing for 24 months
$408.33
Total Paid$9,800
Financing Cost$0
Why It MattersSpreads the cost over two years without increasing the price, as long as the agreement is truly 0% and all terms are followed.
9.99% APR for 60 months
About $208.17
Total PaidAbout $12,490
Financing CostAbout $2,690
Why It MattersThe payment drops by roughly $200 per month compared with the 24-month option, but the system costs about $2,690 more overall.
A longer loan can make a new AC easier to fit into the monthly budget while substantially increasing the total cost. That is why the total of payments matters as much as the advertised monthly payment.
Deferred-interest promotions need an extra level of caution. A plan may advertise no interest for a set period, but if the required balance is not paid by the deadline, previously accrued interest may become due. The exact cost depends on the lender’s agreement, so check the promotional deadline, APR, and deferred-interest terms before accepting the offer.
The best offer is not always the one with the smallest monthly payment. Compare the total amount repaid and the conditions attached to any promotion.
Paying cash usually avoids interest and loan fees, so it often costs less overall. Financing can still be useful when paying the full amount at once would leave too little money available for other needs.
Compare the cash price with the total of payments in the lender disclosure. A longer term may lower the monthly payment while increasing the overall cost. A promotional plan may cost less, but only if you can meet every condition and payment deadline.
Sometimes. A rebate may reduce the invoice before financing or may be issued separately after installation. The answer depends on the current program and lender rules.
Before counting on a rebate, confirm the equipment and customer requirements under the current FPL program. Tax credits follow separate eligibility and filing rules, so check which HVAC incentives may be available in Florida in 2026 before including one in your budget.
Do not subtract a rebate or tax credit from the project cost until you know that the system and household qualify. For advice about your tax situation, speak with a qualified tax professional.
Requirements vary, but lenders commonly ask for identity, contact, residence, income, housing-cost, and project information. It can help to have these ready:
Submit financial and identity details only through the lender’s secure application. Do not send sensitive information through an ordinary contact form or email.
Ask the lender for clear written answers before accepting a financing agreement.
If anything in the disclosure is unclear, ask the lender before signing. The contractor can explain the installation scope, but the lender should answer questions about the financing agreement.
The practical next step is an itemized estimate showing the equipment and work your home needs. That gives you a real project price to use when comparing cash, standard financing, and promotional offers.
Our local AC team can inspect the system and prepare the replacement scope. Once the financing is arranged, knowing what happens during AC replacement can also help you plan for installation day.
To request an itemized estimate before applying, contact our team. You can then compare financing options using the same complete scope instead of choosing a payment plan first and trying to fit the project into it.
Pro Comfort AC LLC
817 SE 9th St
Deerfield Beach, FL 33441
Phone: (954)363-9191
Email: procomfortac@gmail.com
Business Hours
Monday – Sunday: Open 24 Hours
Emergency Service Available
Financing terms, rebate programs, and tax rules can change. Confirm current information with the lender, FPL, and a qualified tax professional before making a decision.